
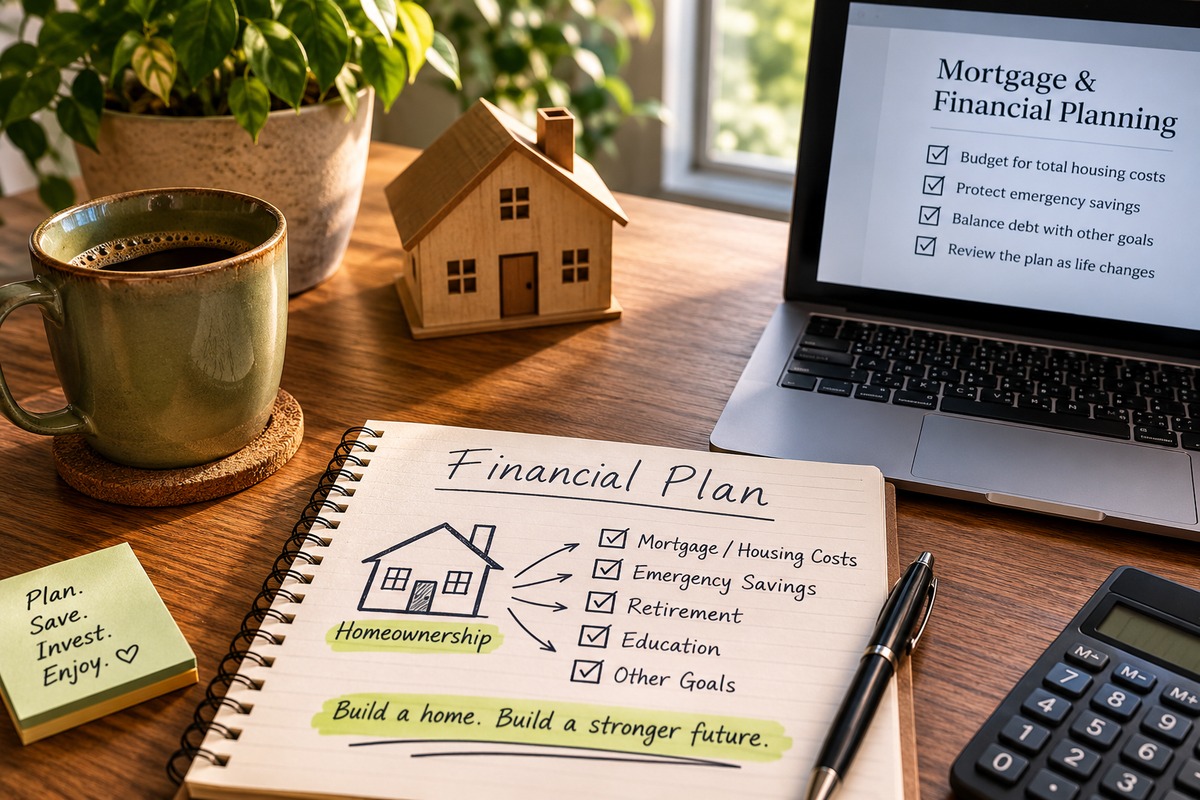
 A mortgage is often the largest financial commitment a household carries, but it should not be viewed separately from the rest of your financial life. Your housing payment affects how much you can save, invest, spend, and prepare for future goals. Understanding how your mortgage fits into your overall plan can help you make decisions that support both homeownership and long-term financial stability.
Start With the Complete Housing Cost
Your mortgage payment may include principal, interest, property taxes, homeowners insurance, and possibly mortgage insurance or homeowners association dues. Maintenance, utilities, and repairs also belong in the housing budget. Looking at the complete cost provides a more accurate picture than focusing only on principal and interest.
Protect Your Emergency Savings
Homeownership creates responsibilities that can arrive without warning. A repair fund and general emergency savings can help you manage unexpected expenses without relying heavily on credit. Your mortgage strategy should leave room to build and maintain those reserves after closing.
Balance Debt With Other Goals
Paying extra toward your mortgage may reduce interest and shorten the loan term, but it is important to consider other priorities. Retirement contributions, education savings, insurance coverage, and higher-interest debt may also require attention. The best approach depends on your complete financial picture rather than one goal alone.
Review the Plan as Life Changes
Income, family needs, career plans, and financial priorities change over time. Reviewing your mortgage regularly can help you decide whether your current payment, loan term, and home still support your goals. A mortgage professional and financial advisor can help you evaluate options when major changes occur.
Your mortgage should support your financial plan, not prevent you from pursuing it. By budgeting for the complete cost of ownership, protecting savings, balancing competing goals, and reviewing your strategy over time, you can make homeownership a stable part of your broader financial future.
 Your mortgage is one of the largest financial commitments you will ever make, yet many homeowners rarely review it after closing. Just as annual physicals help you stay healthy, an annual mortgage checkup can help ensure your loan, insurance, taxes, and financial goals remain aligned. Spending a few minutes reviewing your mortgage each year can uncover opportunities to save money and avoid costly surprises.
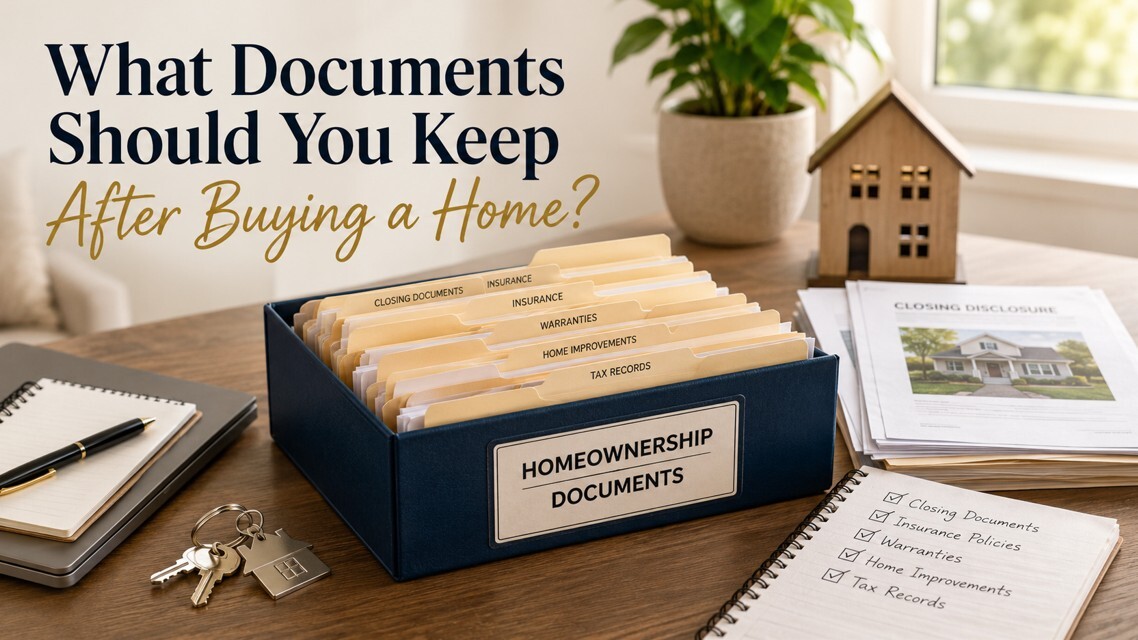 Buying a home comes with a significant amount of paperwork, and once the excitement of closing day has passed, it can be tempting to file everything away without another thought. However, keeping the right documents organized can save time, reduce stress, and protect your investment if questions or unexpected situations arise in the future.
 Buying a home is one of the biggest financial investments most people will ever make but protecting that investment is just as important. Homeowners insurance is often viewed as another monthly bill, yet the coverage you choose can have a significant impact on both your budget and your financial security. Understanding your options can help you balance affordability with the protection your home deserves.
 Many people believe they need a large down payment before they can buy a home. While making a larger down payment can have benefits, it is not the only path to homeownership. Today’s mortgage programs offer a variety of options that allow qualified buyers to purchase a home with much less money upfront than they may expect. Understanding these opportunities can help turn the dream of owning a home into a reality sooner than you think.